Latest News
Welcome to our Blog
Here you’ll find tips, insights, and updates to help you navigate home loans, property, and finance with confidence.
We’d love your input—what topics would you like us to cover? Whether it’s buying your first home, refinancing, or investment strategies, let us know so we can create content that matters to you.
October Newsletter 2026
-
![Aerial view of a tropical beach with turquoise water, sandy shoreline, palm trees, and a few houses amid the greenery.]()
What we've been up to…
It’s been a relatively quiet few months for us. With inflation still proving stubborn and rates continuing to rise, we’re expecting things to remain fairly subdued for a little while yet.
Behind the scenes, we’ve been proactively checking in with clients and reviewing their current lending.
So far, we’ve helped clients:
Secure lower interest rates
Refinance into better deals
Consolidate existing debt
Free up room in the budget for things like a new car
It’s a good reminder that your circumstances — and the lending market — can change. What was a competitive loan a few years ago may not be the best option today.
If it’s been a while since we’ve reviewed your loans, or you’re wondering if there’s anything that could be improved, get in touch. Sometimes a review results in a change; sometimes it simply confirms you’re in a good position. Either way, it’s worth knowing.
Meanwhile, at home…
After talking about money, mortgages and budgets all day, we’ve finally bitten the bullet and decided to get a solar battery!
We’re hoping it will take a little pressure off those ever-present energy bills, and we’re also making use of the government’s current home battery incentives.
We’ve gone with PSC Energy and have had a really good experience so far. If you’re thinking about solar or a battery, we’re happy to pass on our consultant’s details.
Other than that, it’s business as usual — ticking along, spending time with the kids and getting out camping whenever we can.
As always, get in touch for a chat!
Dean & Kristen
-
![A woman with blonde hair resting her head on her folded arms on a desk covered with open books, appearing exhausted or stressed, with illustrated scribbles and sad face icons above her head.]()
Which Lender? Our Partner Spotlight.
This quarter we're shining the spotlight on Athena, an Australian non-bank lender launched in 2019 with a focus on making home loans simpler, more competitive and transparent.
The best bits
✅ No ongoing loan fees — no annual or ongoing maintenance fees on its flagship home loans.
✅ Competitive rates — Athena aims to avoid the traditional “loyalty tax”, with existing customers continuing to receive competitive rates.
✅ Digital & simple — applications and loan management are primarily online.
✅ Rates that can reduce — eligible borrowers can receive automatic rate reductions as they build equity and reduce their LVR.
✅ Strong refinancing option — particularly worth considering for borrowers looking to move away from a higher-cost loan.
✅ Certified B Corp — committed to standards around social and environmental performance, accountability and transparency.
A couple of things to consider
No branches — everything is handled online or over the phone.
Simpler product range — Athena focuses primarily on home loans rather than offering a full suite of banking products.
Check the features — make sure the loan structure and features suit your individual circumstances.
Thinking about refinancing or wondering whether Athena could work for you? Get in touch and we can compare the options with your current loan.
-
![An aerial view of a neighborhood showing multiple houses with different roof styles and colors, along with streets, trees, and parked cars.]()
Why Are Rates Still Going Up When Everyone Feels Like They’re Cutting Back?
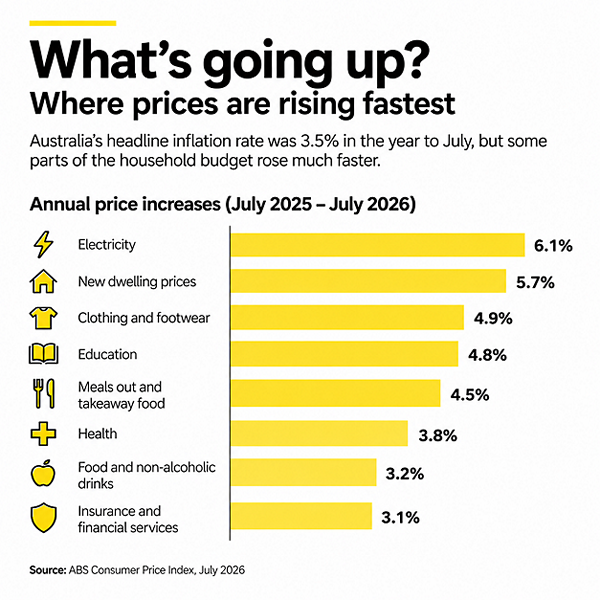
If it feels like everyone is tightening their belts, putting off big purchases and watching their spending, you might reasonably wonder: why are interest rates still going up?
Australian households have been dealing with higher prices and mortgage repayments for years, yet inflation remains stubborn.
The RBA has now increased the cash rate to 4.60%, saying inflation remains too high and demand needs to slow further.
So, what’s going on?
Inflation doesn't mean prices are falling
When inflation comes down, it doesn't mean prices go back to where they were. It simply means they're rising more slowly.
That’s why the cost-of-living squeeze can continue even when inflation starts to ease. Your groceries, electricity and other household costs can still be significantly higher than they were a few years ago.
CommBank recently looked at why inflation remains persistent, even while many households are feeling the pinch.
But aren't households cutting back?
Yes — but not everyone is experiencing the economy in the same way.
CommBank’s data shows spending varies significantly between age groups, with spending among Australians aged 65+ growing faster than among younger households.
For someone with a large mortgage, higher rates can quickly eat into the monthly budget. For someone without a mortgage, higher rates can have a very different impact — particularly if they have savings earning interest.
And inflation isn’t only about household spending. Energy costs, business costs, productivity and other economic factors can all play a part.
What happens to repayments for a typical mortgage?
A 0.25% rate increase can make a noticeable difference.
As a rough illustration:
$500,000 mortgage → approximately $80–$100 extra per monthThe exact impact depends on your interest rate, loan term and structure, but it shows how quickly small rate movements can add up.
So what does this mean for homeowners?
For anyone with a mortgage, the economic debate can feel pretty abstract. What matters is what it means for your household budget.
That’s why we think it’s worth reviewing your lending position from time to time.
A review might uncover:
A more competitive interest rate
An opportunity to refinance
Debt that could be consolidated
A loan structure that better suits your current situation
Or simply reassurance that you’re already in a good position
We can't control what the RBA does or where inflation goes next.
But we can make sure our own finances are set up as well as possible for the environment we're in.
Sometimes, that starts with simply taking another look at your mortgage.
-
![A couple holding hands while walking outdoors on a sidewalk during daytime.]()
Why Are We So Obsessed With Having a “Nice” Home?
When did having a nice home become having a perfect home?
Scroll through Instagram and Pinterest and it's easy to feel like everyone else has spotless kitchens, perfectly styled living rooms and beautifully organised homes.
Then you look around your own house.
There's washing on the couch, toys on the floor and something sticky on the kitchen bench.
Welcome to real life.
The problem isn't wanting a beautiful home. It's that we're comparing our everyday lives with carefully curated snapshots of someone else's.
As one interior designer recently pointed out, those picture-perfect homes often leave out the very things that come with actually living in a house — laundry, toys, chargers, dirty dishes and general clutter. The Sun's article is a fun read on the subject.
And once you have kids, the idea of a permanently perfect home becomes even more unrealistic.
There will be fingerprints. Lego. School bags. Crumbs. A couch that's actually used.And that's okay.
Maybe the best family home isn't the one that looks best in a photograph. It's the one that works best for the people living in it.
There's another thing we've realised: the imperfections we notice are usually the ones nobody else sees.
You notice the mark on the wall because you've walked past it every day.
You see the clutter.
Your friends coming over for dinner probably don't.
They see your home. They see the people in it. They're probably much more interested in the conversation than whether your cushions match.So enjoy the decorating. Renovate if you want to. Make your home somewhere you love being.
But maybe we can take a little pressure off ourselves to make it look perfect.
Because your house isn't a showroom.
It's somewhere to live and a home.
News
-
SMSF
3 August 2026
There’s been a lot of talk about the changes to SMSF property lending — but SMSF lending isn’t disappearing altogether.
From 10 August 2026, Self-Managed Super Funds can no longer use new Limited Recourse Borrowing Arrangements (LRBAs) to purchase residential property.
But there are still options:
• If your residential property contract is signed and exchanged by 9 August, the purchase can still proceed under the transitional arrangements — even if settlement occurs later.
• Existing SMSF residential loans are grandfathered- meaning existing rules stay in place.
• We can still assist with refinancing existing SMSF residential loans.
• Commercial/business property lending through an SMSF continues, where the property meets the relevant SMSF rules.
So, while the rules are changing, SMSF lending is certainly not off the table.
If you have just purchased, already have an SMSF loan, are considering refinancing, or want to explore commercial property through your SMSF, get in touch with us to see what options may be available.
General information only. SMSF, tax and investment strategies should be discussed with your accountant or licensed financial adviser.
-
Asset finance
3 June 2026
Most people know us for home loans, but did you know we can also help with asset finance and personal loans?
If you're upgrading your car, purchasing business equipment, or planning your next holiday, we can help find a finance solution that suits your needs.
Asset finance and personal loans can be used for:
Cars, Utes and motorcycles
Caravans and motorhomes
Boats and jet skis
Business equipment and machinery
Trucks and commercial vehicles
Technology and office equipment
Home improvements
Debt consolidation
Personal expenses
Holidays
Weddings
Just like with home loans, we compare options to help find a competitive solution that works for your situation.
If you're considering a purchase or would simply like to understand your options, we'd be happy to have a chat.
July Newsletter 2026
-
![Aerial view of a tropical beach with turquoise water, sandy shoreline, palm trees, and a few houses amid the greenery.]()
Hi from the USA!
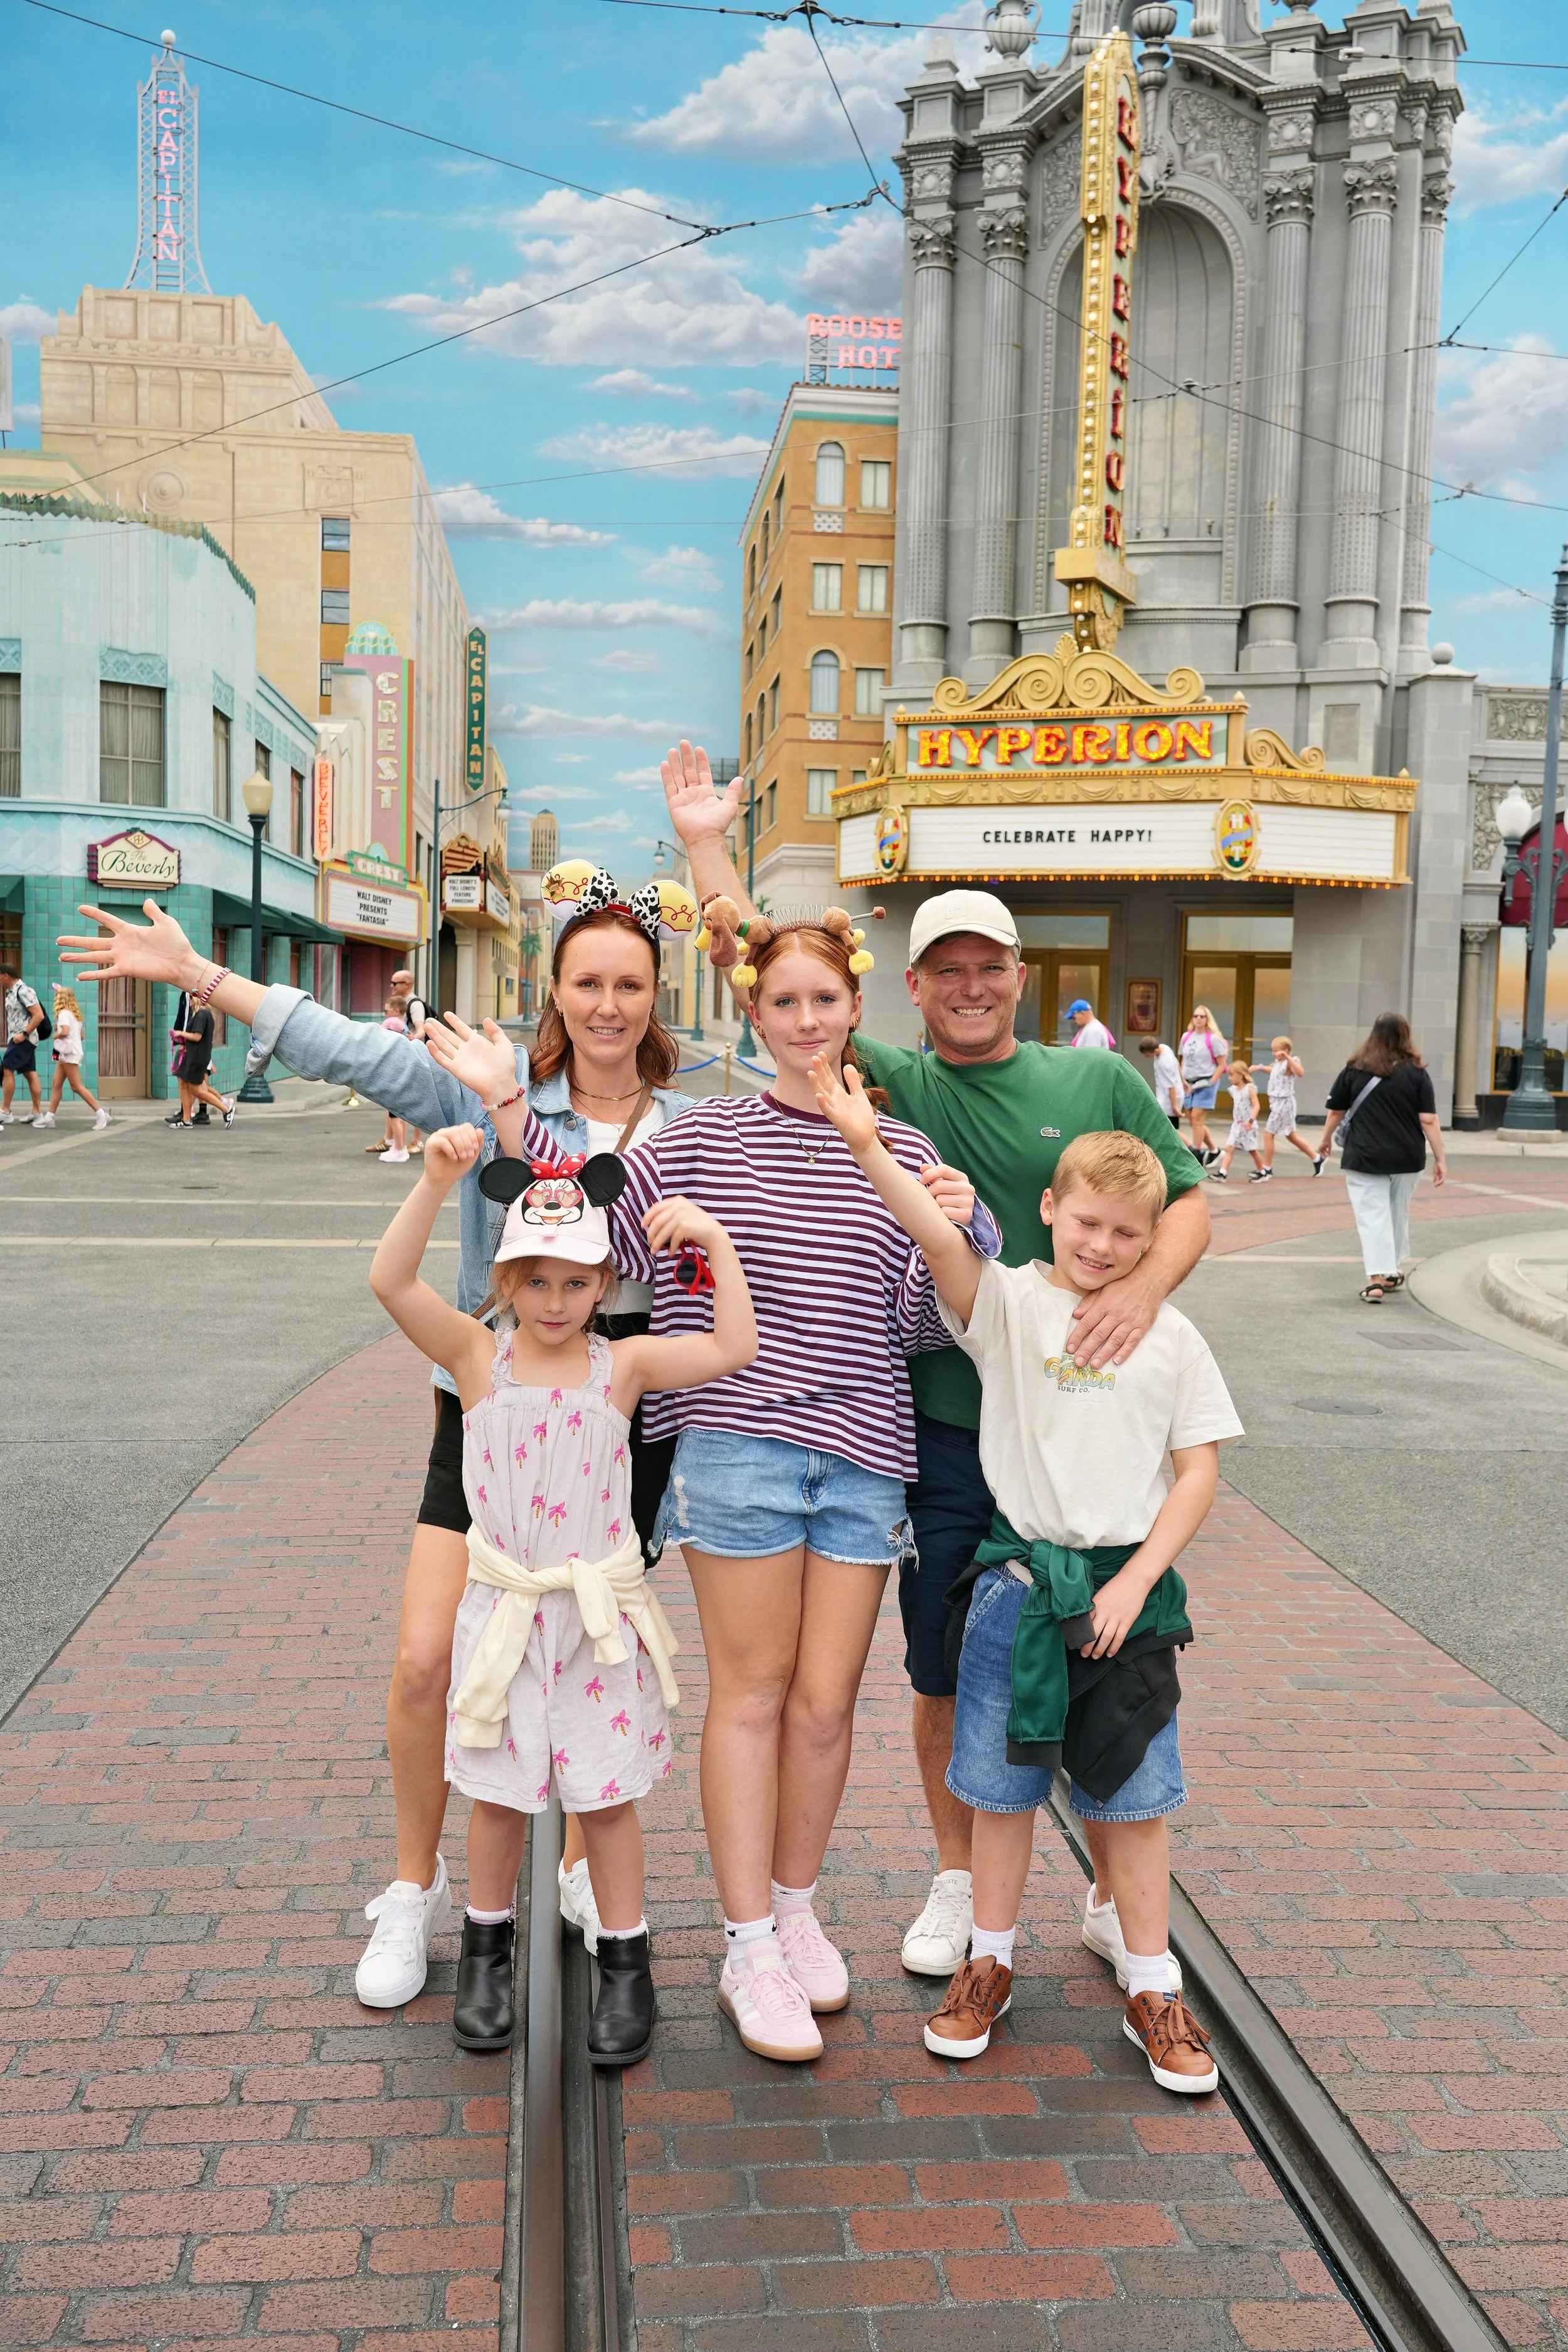
As you're reading this, we're taking a little family adventure through the USA. The kids have had an absolute ball at Disney, we've soaked up the incredible World Cup atmosphere, and swimming with the sealions was epic.
The exchange rate with the US dollar is hitting hard though!
Back home, it's fair to say the past few months have been a bit of a rollercoaster. Between oil prices, government budget changes and ongoing political unrest overseas, many people have understandably hit the pause button when it comes to big financial decisions. The good news? We're starting to see confidence return, enquiry levels pick up, and lenders becoming increasingly competitive again.
One area we had been expanding in was SMSF lending.
Unfortunately recent changes mean Aussies can no longer access their super to buy properties. This is a disappointing change and comes into effect from 9th August.
Firstmac CEO Marie Mortimer said-
“SMSF borrowers are not wealthy people. They are people who do not have a deposit outside of super and are unable to purchase a home,” she said.
“SMSF borrowing offers their only hope of buying a home for their retirement. This change will consign a segment of the community to being lifelong renters.”
If you managed to secure a signed and exchanged contract of sale, dated prior to 9 August we can still help.
With that in mind, here are a few of the deals currently on offer:
• Bank of China: $2,888 cashback for eligible new and refinance loans over $400,000
• Peoples First Bank: $1,000 rebate on eligible loans
• ME Bank: $3,000 cashback for eligible refinance loans over $700,000
• ANZ: $3,000 cashback for eligible first home buyers with loans over $250,000As always, if you're wondering whether one of these offers could work for you, we'd love to have a chat. In the meantime, we'll be trying to convince the kids that Disneyland isn't actually a reasonable benchmark for future family holidays!
-
![A woman with blonde hair resting her head on her folded arms on a desk covered with open books, appearing exhausted or stressed, with illustrated scribbles and sad face icons above her head.]()
Which Lender? Our Partner Spotlight.
Self-employed? RedZed is one of our go-to lenders for business owners, sole traders and entrepreneurs who don't always fit the traditional bank mould.
What we love about RedZed is their common-sense approach. They understand that self-employed income isn't always straightforward and offer flexible ways to verify income, including BAS statements, accountant declarations and business bank statements.
They're also a great option for refinancing, accessing equity, debt consolidation and tax debt solutions.
What's New?
RedZed has recently introduced more competitive Prime pricing for eligible borrowers and continues to expand its RedZed Benefits program, giving customers access to a range of lifestyle perks and discounts.
If you've ever been told your situation is "too complicated", it may be worth another conversation. The right lender can make all the difference.
-
![An aerial view of a neighborhood showing multiple houses with different roof styles and colors, along with streets, trees, and parked cars.]()
Is the Aussie Backyard Making a Comeback?
Whether it's a veggie patch, a fire pit, or finally building that deck you've been talking about for years, home isn't just where you live—it's where life happens. If improving your space is on your wish list, we'd be happy to chat through the finance options available to you.
With travel costs rising and people spending more time at home, Australians are investing in their own slice of paradise. Think veggie gardens, fire pits, plunge pools and pizza ovens. The backyard is no longer just grass to mow—it's becoming an extension of the home.
Renovation loans, equity releases, or simply making the most of the home you already own.
-
![A couple holding hands while walking outdoors on a sidewalk during daytime.]()
Is the Property Market Finally Finding Its Feet?
After a few months of uncertainty driven by global events, budget announcements and fluctuating consumer confidence, the Australian property market appears to be settling into a more balanced rhythm.
Rather than the dramatic highs and lows we've seen in recent years, we're seeing steady buyer activity, improving confidence and lenders competing strongly for quality borrowers.
For buyers, refinancers and investors alike, this can create opportunities. With cashback offers, policy changes and competitive pricing returning to the market, it's a timely reminder that waiting for the "perfect" moment isn't always the best strategy.
One new change to consider though is changes to supply for renters due to the self managed super fund changes.
Property has always been a long-term game, and for many Australians, the right time to act is when the decision aligns with their personal goals and circumstances.

April Newsletter 2026
-
![Aerial view of a tropical beach with turquoise water, sandy shoreline, palm trees, and a few houses amid the greenery.]()
Happy Easter from Blue Sky Mortgage Solutions.
Since our last update in January, it’s been a strong start to 2026.
We’ve welcomed 12 new clients – 33% via social media and notably 67% through referrals. A BIG Thank you for your continued support and for trusting us with your friends and family.
We also enjoyed running our recent Easter competition, with our winner taking home a well-deserved chocolate hamper.
So far this year, we’ve worked with a wide range of lenders including Newcastle Permanent, Macquarie Bank, Commonwealth Bank, RedZed, Suncorp, People’s First Bank, St George, Westpac, ANZ and Pepper Money, allowing us to match clients with competitive and suitable lending options.
Behind the scenes, we’ve been focused on staying ahead of industry changes. Dean recently attended a professional development day in Sydney with Connective, covering AI, compliance and key lending trends, along with ongoing BDM catch-ups and lender updates to ensure we’re providing current, well-informed advice.
Giving back remains important to us. Kristen has been further developing her volunteer firefighting skills and was recently featured by Women and Firefighting Australasia. Dean continues his regular blood donations with the Red Cross, and we’re proud supporters of the McGrath Foundation cancer care nurses.
Over the Easter period, we’ll be spending some time locally with family and friends, but remain available as always.
Dean & Kristen
-
![A woman with blonde hair resting her head on her folded arms on a desk covered with open books, appearing exhausted or stressed, with illustrated scribbles and sad face icons above her head.]()
Which Lender? Our Partner Spotlight.
This month we’re highlighting ANZ, one of Australia’s Big 4 banks, offering competitive rates within the major lender space.
ANZ is now participating in the Government’s 5% deposit scheme, giving eligible first home buyers more choice and flexibility, along with the benefit of entering the market sooner with a smaller deposit.
For those who don’t qualify for the scheme but are still looking to purchase their first home, ANZ is currently offering a $3,000 cashback for eligible applicants (terms and conditions apply).
In the current financial climate, both options can provide meaningful support -whether it’s reducing the upfront deposit required or putting cash back in your pocket a $3,000 cashback can make a real difference, helping to cover upfront costs like moving expenses, legal fees or furnishing your new home.
They have also recently simplified some of their application requirements, improving application time and ease.
As always, we can help assess whether ANZ and these offers are the right fit for your situation.
-
![An aerial view of a neighborhood showing multiple houses with different roof styles and colors, along with streets, trees, and parked cars.]()
How can I improve my Household Budget?
The big news in the media right now is the demise of the Kyle and Jackie O show… sorry, we mean the economy, cost of living and fuel prices.
The recent national announcement by the Prime Minister offered little in the way of a clear financial plan or meaningful relief for everyday Australians.
Cost of living pressures remain front of mind for many households. Inflation continues to push up everyday expenses, and the Reserve Bank of Australia has responded with multiple rate increases, most of which have been passed on by lenders in full.
For borrowers, this means higher repayments and tighter cash flow. In this environment, it’s worth reviewing your loan to ensure your rate and structure remain competitive. There may be opportunities to refinance, consolidate debts, or simply improve overall cash flow.
It’s also a good time to revisit your household budget. Even small changes can make a noticeable difference:
Review your credit card and bank statements over the past 3 months to identify spending patterns and areas to cut back.
Review your current loans – we can assist with checking rates, cashback offers and lender promotions
Plan meals ahead of time to reduce unnecessary grocery spending
Re-shop providers for utilities such as energy and insurance
Review your energy plan to ensure it suits your usage
Audit streaming services and paid apps – cancel anything you’re not regularly using
If you have multiple debts, consider whether consolidation could simplify repayments and reduce interest
Build a savings buffer, even gradually, to help manage unexpected expensesIf you’d like help reviewing your current lending or exploring ways to improve your cash flow, feel free to get in touch.
-
![A couple holding hands while walking outdoors on a sidewalk during daytime.]()
What does $1M Buy You Right Now?
With property shifting across the country, it’s always interesting to see how far $1 million actually goes.
Recent data from Domain House Price Report shows that many capital cities have now pushed beyond the $1M median mark for houses, highlighting just how much the market has shifted in recent years.
What This Means
The gap between markets has narrowed significantly. Not long ago, only Sydney sat above the $1M mark; today, most capital cities have joined what’s effectively become the “million-dollar club.”
At the same time, units are increasingly becoming the entry point for many buyers, particularly in higher-priced cities, as affordability pressures continue to shape buyer behaviour.
For buyers, this reinforces an important point: Your strategy matters just as much as your budget.
That might mean:
Adjusting location (metro vs regional)
Considering property type (house vs unit)
Or structuring your loan to maximise borrowing capacity$1 million is still a significant budget -but what it buys you today depends entirely on where (and how) you choose to use it.
If you’re weighing up your options, we can help you map out what your borrowing capacity looks like and how far it can go in today’s market.
January Newsletter 2026
-
![Aerial view of a tropical beach with turquoise water, sandy shoreline, palm trees, and a few houses amid the greenery.]()
Welcome to 2026, and Happy New Year!
As we step into 2026, we wanted to say thank you for your support over the past year.
2025 was a big one for us, our first year in business, alongside life with three kids, one energetic dog, and a very full family calendar. We squeezed in a holiday to Fiji, a country Christmas with family in Cowra, and plenty of school-holiday chaos in between. Through it all, your trust, patience, and referrals meant more to us than we can say.
Starting a brokerage has been exciting and challenging in equal measure. Dean remains ever-optimistic and firmly in growth mode, while Kristen has juggled business life alongside a busy bushfire season with the RFS. We’re incredibly grateful to our clients who backed us from day one and helped make our first year such a positive one.
Looking ahead to 2026, our focus remains: To help more people (which is why your advocacy is so important) and to grow in the Commercial and Self-Managed Superannuation lending space.
We look forward to continuing to support you with proactive reviews, clear guidance, and mortgage advice that evolves as your life does.
Thank you again for being part of our journey. We look forward to another year of working together.
Dean & Kristen
-
![A woman with blonde hair resting her head on her folded arms on a desk covered with open books, appearing exhausted or stressed, with illustrated scribbles and sad face icons above her head.]()
Which Lender? Partner Spotlight.
People First Bank is a customer-owned mutual bank formed through the merger of People’s Choice and Heritage Bank, bringing together the strength of two well-established Australian institutions. This merger is currently taking place.
As a mutual bank, People First Bank is owned by its members rather than shareholders, allowing it to focus on delivering long-term value, competitive products, and positive outcomes for its customers and communities.
At present, we are actively refinancing clients to People Choice Bank, driven by their highly competitive lending offerings.
Eligible borrowers may access a $1,000 cashback rebate per loan offering a nice little incentive to join!
(For People’s Choice Bank, Broker loans, T’s & Cs apply).
People First Bank is also offering some of the most competitive rates in the market right now, including:
Owner-occupied, Principal & Interest loans from 5.24%
Investment, Principal & Interest loans from 5.39%
(For People’s Choice Bank, Eligibility criteria apply, T’s & Cs apply).
-
![An aerial view of a neighborhood showing multiple houses with different roof styles and colors, along with streets, trees, and parked cars.]()
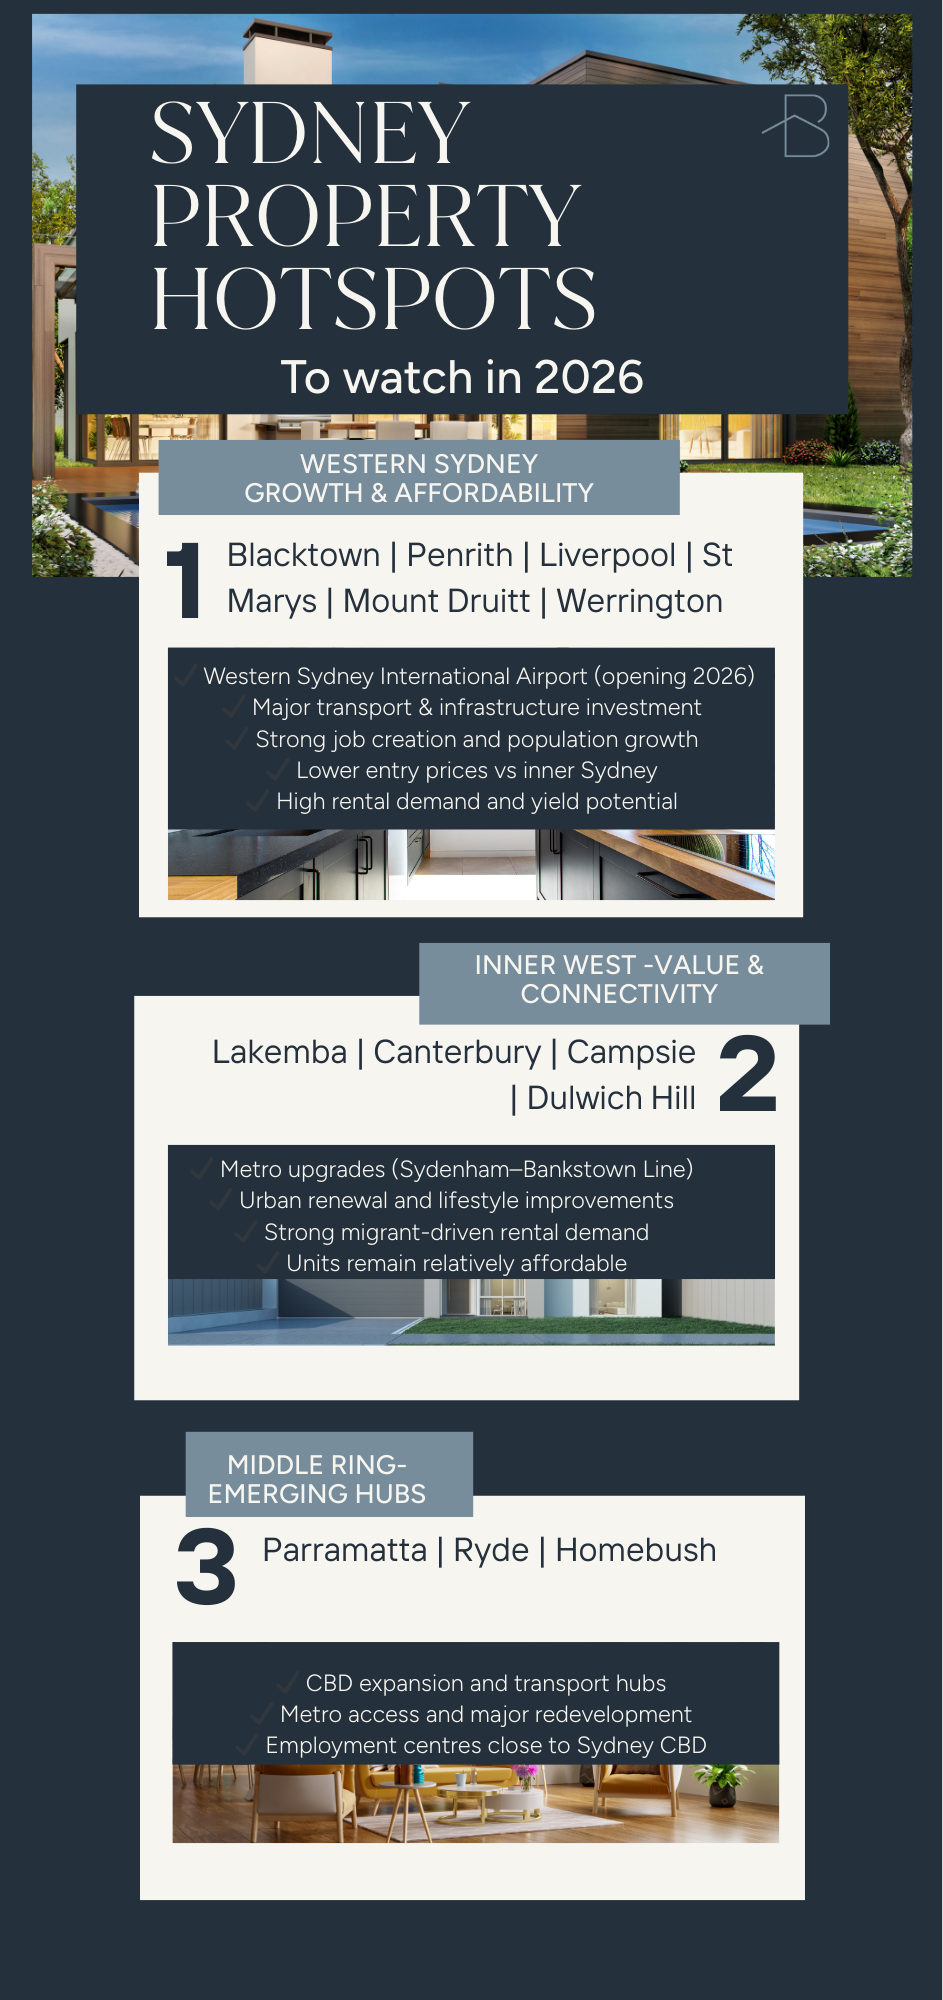
What hotspots to watch in Sydney’s Property Market 2026?
(Based on forecasts from SQM Research, API Magazine, and realestate.com.au)
Western Sydney is leading the forecasts, driven by the opening of the Western Sydney International Airport in 2026 and major infrastructure investment. Suburbs such as Blacktown, Penrith, Liverpool, St Marys, Mount Druitt, and Werrington are benefiting from improved transport links, job creation, population growth, and more affordable entry prices compared to inner Sydney.
In the Inner West, suburbs including Lakemba, Canterbury, Campsie, and Dulwich Hill continue to attract attention due to metro upgrades, urban renewal projects, and strong rental demand, particularly for units that remain relatively affordable.
The Eastern Suburbs, while premium-priced, are expected to remain resilient. Areas such as Bondi, Coogee, and Randwick are supported by limited housing supply, strong lifestyle demand, and long-term capital preservation.
Finally, middle-ring hubs like Parramatta, Ryde, and Homebush are emerging as growth areas thanks to CBD expansion, metro access, and major redevelopment projects.
Quick Buyer Guide
Chasing capital growth? Western Sydney & the Inner West
Looking for balance (growth + yield)? Lakemba, Campsie & Canterbury
Seeking stability and long-term value? Eastern Suburbs
If you’re considering buying or refinancing in 2026, focusing on infrastructure-backed locations and well-connected suburbs may position you strongly for the years ahead.
-
![A couple holding hands while walking outdoors on a sidewalk during daytime.]()
What is the Big Four Banks’ 2026 Interest Rate Outlook?
Australia’s Big Four banks are divided on interest rate expectations for 2026: CBA and NAB are forecasting potential early rate hikes, while ANZ expects rates to hold, and Westpac now leans toward stability after previously predicting cuts. Overall, significant rate reductions seem unlikely this year.
Bank-by-Bank Snapshot:
Commonwealth Bank (CBA): Forecasts a 0.25% rate hike in February 2026 to address persistent inflation.
“The economy has picked up more momentum than expected, and that strength is keeping inflation from easing. A small rate increase in February would guide inflation back toward the RBA’s target range of 2-3 per cent,” said Commonwealth Bank Head of Australian Economics Belinda Allen.
National Australia Bank (NAB): More hawkish, predicting two 0.25% hikes in February and May 2026.
ANZ: Expects rates to stay on hold for the first half of 2026, citing balanced labour markets and moderate growth. Some risk of an early hike remains. ANZ’s head of Australian economics Adam Boyton said "We no longer see one final rate cut from the RBA in the first half of 2026, given recent inflation pressures,"
Westpac: Now anticipates rates holding, after previously expecting cuts, with risks on both sides.
Our View – Blue Sky Mortgage Solutions
Looking at historical cycles, we anticipate no rate movement until April-May, and then potentially a rate decrease. This outlook differs from most economists, but we the cash rate is currently in the target space and we are seeing slower economic growth- so the RBA may be more likely to decrease rates.The first RBA policy meeting of 2026 will run from Monday, February 2, to Tuesday, February 3, with the interest rate decision announced at 2:30pm AEDT.
Everyone’s circumstances are different, so please feel free to reach out and start a discussion with us.

October Newsletter 2025
-
![Aerial view of a tropical beach with turquoise water, sandy shoreline, palm trees, and a few houses amid the greenery.]()
What's Been Happening
Spring, School Holidays & Exciting Updates!
The school holidays are in full chaotic swing, and we’re just about to depart for a much-needed getaway to Fiji. Don’t worry — we’ll still be accessible while away… probably by the pool, cocktail in hand! 🍹
Here’s a snapshot of what we’ve been up to over the past three months:
Client Growth: Since our last newsletter, we’ve welcomed 13 new clients into the Blue Sky family — an unlucky number for some, but certainly lucky for us!
Refinance Rebate Market: ANZ has become the last major bank to exit the refinance rebate space. This leaves only ME Bank, People’s First Bank, and Bank of China offering cash back options:
ME Bank: $3,000 cashback on home loans ≥ $700,000 (owner-occupier and investor; max LVR 80%)
People First Bank: $1,000 cashback on refinances ≥ $500,000 (LVR < 80%; offer until 30 June 2026)
Bank of China: $2,000 cashback on loans ≥ $400,000 (applies to new purchases or refinances)
Refinance Wins:
We recently saved a client 0.89% on her ANZ refinance, putting nearly $5,000 back in her pocket each year.Pricing Wins:
With our client review process, we saved another client $3,124 p.a.It’s been a busy few months, and we love helping our clients make the most of their home loans — whether it’s buying, refinancing, or finding the best cash-back deals.
The 5% deposit scheme will help more first-home buyers from today - but the market will 'explode'
-
![A woman with blonde hair resting her head on her folded arms on a desk covered with open books, appearing exhausted or stressed, with illustrated scribbles and sad face icons above her head.]()
Which Lender? Partner Spotlight.
CommBanks New Options
Buying a Home with HELP Debt –
If you have HELP (Higher Education Loan Program) debt, CBA has introduced new assessment options that could make a big difference to your borrowing power.
Effective 9 April, CBA now offers two new ways to treat HELP debt when reviewing home and investment loan applications.
How It Works
Option One:
If your HELP debt can be repaid within 12 months (based on income and HELP deductions), it’s excluded entirely from your serviceability assessment.Option Two:
If repayment takes 1–5 years, HELP repayments are included, but CBA applies a reduced 1% serviceability buffer (down from the standard 3%).This makes it easier to qualify for a home loan and can increase your borrowing capacity, particularly for first home buyers.
Joint Applications
If two applicants have different HELP debt situations, CBA applies Option Two for both, meaning:
HELP repayments are still included
A 1% assessment buffer appliesWho’s Not Eligible
These new HELP servicing options do not apply to:
Bridging loans
Loans via companies or trusts
Loans with “servicing” guarantors
Applications requesting other servicing exceptions (e.g., REA, MLE, Commitment Apportioning)How Much More Could You Borrow?
These changes could significantly boost your borrowing power. For example:Next Steps
If you have HELP debt and are ready to buy your first home (or upgrade), we can help you:
-Assess your eligibility under CBA’s new options
-Calculate your borrowing power accurately
-Guide you through pre-approval and lender selectionContact us today to see how CBA’s new HELP debt options could help you buy sooner.
-
![An aerial view of a neighborhood showing multiple houses with different roof styles and colors, along with streets, trees, and parked cars.]()
What's happening in the NSW Property Market?
NSW Property Market Update – Spring 2025
The Australian property market is showing strong signs of momentum heading into spring — with NSW leading the charge.
Home values are rising, up 0.9% last month and 4% year-on-year, pushing the average dwelling price to just over $1 million.
Auction activity is surging, with clearance rates hitting 77.9%, the highest since 2021.
The RBA’s recent rate cut to 4.10% is helping ease mortgage stress and spark fresh buyer demand.
But with a 6% drop in new housing approvals, experts warn that supply shortages could continue to drive prices higher.
According to News.com.au, Australia could be heading into a new real estate boom, as demand outpaces construction and more buyers re-enter the market.
Click here to read the full article
There has also been a lot of speculation about the Government’s 5% Deposit scheme causing a property market price explosion.
-
![A couple holding hands while walking outdoors on a sidewalk during daytime.]()
The New 5% Deposit Scheme – Now Live
From 1 October, the Federal Government’s new 5% Deposit Scheme officially launched — and it’s already opening the door for more Australians to enter home ownership.
The updated scheme has been redesigned to remove many of the barriers first home buyers have faced, making it easier to buy with a smaller deposit and avoid costly Lenders Mortgage Insurance (LMI).
What’s Changed
The 2025 updates are some of the most significant to date:-No income caps – more Australians now qualify
-Unlimited places – no waiting lists or missed opportunities
-Higher property price caps – up to $1.5 million in NSW metro and regional centres
-Two streams available – one for general buyers and another specifically for single parents
With broader eligibility and no cap on spaces, the scheme could help thousands who were previously locked out of the market — particularly in higher-priced areas where saving a 20% deposit can take years.
If you’ve been thinking about buying your first home — or getting back into the market after some time — now could be the ideal opportunity to take another look.
Scheme Tools and Resources
To explore the full details, you can visit:
🏠 First Home Buyers NSW Government website
📊 Price Cap Tables – to see how much you can borrow while still accessing the scheme
❓ Government FAQs – find detailed answers to common questions


July Newsletter 2025
-
![A decorated birthday cake with a single lit candle, red berries on top, surrounded by four champagne glasses and colorful confetti on a white table.]()
Month in business
After an exciting first month in business, we want to thank you—our valued clients, for joining us on this new journey. Your continued trust and support means the world to us.
We are here to provide you with the same specialist advice and personalised service you've received to date.
We appreciate all your recommendations and kind words.
We’re just getting started, and we can’t wait to see what’s ahead!
-
![Bright blue sky with scattered white clouds.]()
Which lender? Partner Spotlight.
Own Home’s Buyer’s Agent Service
Free with Deposit Boost loans
One of our lending partners, Own Home, is offering a powerful incentive for eligible buyers: a full buyer’s agent service, free when utilising on of their Deposit Boost Loans.
What’s included — at no cost to you:
1-on-1 support from licensed agents
4 professional property reports
(valued at $2,400)
Expert price negotiation & auction support
Tailored market research & suburb guides
Weekly updates throughout the journeyNormally valued at $13,200
Now $0 with a Deposit Boost loan.
Own Home clients buy 6x faster than the average first home buyer (just 32 days on average).
Get in touch to find out if this could be right for you or someone you know.
Terms and conditions apply. Regular lending criteria applies. Visit Own Home for their full terms and conditions.
-
![Surfers in the ocean waves during sunset with foreground leaves and bokeh effect.]()
Sea Change?
Kiama’s coastal charm is calling—house prices are still $177K below their 2022 peak, making it a great time to buy.
With rising interest in areas like Minnamurra, where the city feels far away and you can imagine diving off the deck for a morning swim, now could be your chance to make the dream a reality.
House values are rising again but still offer great value compared to pandemic highs.
Thinking of making a move? We can help with finance options.
Read the full article → on Domain
-
![People walking past the Reserve Bank of Australia building, with some motion blur from a passing vehicle in the foreground.]()
Is a Rate Cut on the Horizon?
Inflation is cooling, and Westpac has joined CBA in predicting interest rate cuts as early as July.
The latest data shows inflation dropped to 2.1% in May—raising hopes for lower mortgage rates. A 0.25% cut could save around $178/month on a $600,000 loan.
What does this mean for you?
Potential relief—but not all lenders pass on the full cut.
Contact me for your annual review. Description goes here